Please cite an example of ***An Investment or Insurance Product* **that is FDIC or Federally insured? I can't think of one...
Wells Fargo savings and checking products including CDs & Money Markets will continue to be FDIC insured up to $250K total per SSN, although that raising that number is being discussed.
Here you go [USER=127]@Rick67[/USER]. We all know damn well why you can't give an example of an investment or insurance product that's FDIC insured. It's because NONE are, ergo the Wells Fargo disclaimer, which is nothing new. Anytime you open a non-FDIC insured account, the bank/broker has to tell you. Guess you haven't opened any of those uninsured investment things in a while...
From the FDIC website:
Q: Is every financial product at a bank covered by the FDIC? * A: No. FDIC deposit insurance only covers certain deposit products, such as checking and savings accounts, money market deposit accounts (MMDAs), and certificates of deposit (CDs). See [“Are My Accounts Insured by the FDIC?”]('https://www.fdic.gov/resources/deposit-insurance/financial-products-insured/') for a full list of the types of deposit products that are covered by FDIC insurance and the amount of deposit insurance coverage that may be available under FDIC’s different ownership categories.*
Shall I go to heaven or a-fishing? - H. D. Thoreau Veni. Vidi. Cepi. - with apologies to Gaius Julius Caesar
Here’s a trend for you to watch. WOKE banks not being FDIC approved.
Nothing ominous about that announcement from Wells Fargo, just a normal disclaimer notification from any bank.
From the FDIC Website:
[HEADING=1]The FDIC covers[/HEADING] [LIST] [*]Checking accounts [*]Negotiable Order of Withdrawal (NOW) accounts [*]Savings accounts [*]Money Market Deposit Accounts (MMDAs) [*]Time deposits such as certificates of deposit (CDs) [*]Cashier's checks, money orders, and other official items issued by a bank [/LIST] [HEADING=1]The FDIC does not cover[/HEADING] [LIST] [*]Stock investments [*]Bond investments [*]Mutual funds [*]Crypto Assets [*]Life insurance policies [*]Annuities [*]Municipal securities [*]Safe deposit boxes or their contents []U.S. Treasury bills, bonds or notes [/LIST] *These investments are backed by the full faith and credit of the U.S. government.
Depositors do not need to apply for FDIC insurance. Coverage is automatic whenever a deposit account is opened at an FDIC-insured bank or financial institution. If you are interested in FDIC deposit insurance coverage, simply make sure you are placing your funds in a deposit product at the bank.
[HEADING=1]COVERAGE LIMITS[/HEADING] The standard insurance amount is $250,000 per depositor, per insured bank, for each account ownership category.
The FDIC provides separate coverage for deposits held in different account ownership categories. Depositors may qualify for coverage over $250,000 if they have funds in different ownership categories and all FDIC requirements are met.
All deposits that an accountholder has in the same ownership category at the same bank are added together and insured up to the standard insurance amount.
[HEADING=1]WHEN A BANK FAILS[/HEADING] A bank failure is the closing of a bank by a federal or state banking regulatory agency, generally resulting from a bank's inability to meet its obligations to depositors and others. In the unlikely event of a bank failure, the FDIC acts quickly to ensure depositors get prompt access to their insured deposits.
FDIC deposit insurance covers the balance of each depositor's account, dollar-for-dollar, up to the insurance limit, including principal and any accrued interest through the date of the insured bank's closing.
The FDIC acts in two capacities following a bank failure:
[LIST=1] [*]As the "Insurer" of the bank's deposits, the FDIC pays deposit insurance to the depositors up to the insurance limit. [*]As the "Receiver" of the failed bank, the FDIC assumes the task of collecting and selling the assets of the failed bank and settling its debts, including claims for deposits in excess of the insured limit. [/LIST]
Shall I go to heaven or a-fishing? - H. D. Thoreau Veni. Vidi. Cepi. - with apologies to Gaius Julius Caesar
The end of the rainbow is actually a lot of pain. This is all by design...I think I wrote a post thread about it last year.
FedCoin and Central Bank Digital Currencies coming within 24 months, (these are programmable digital dollars, what you can spend, how you can spend it and all centrally tracked by your dear Government) which for all intents and purposes will wipe out any financial privacy, freedom and choice for every citizen. Slave state mark of the beast stuff prophesized in Revelations.
Here’s a trend for you to watch. WOKE banks not being FDIC approved.
Investment Accounts at WF Securities are covered by SIPC up to 250K, just like any bokerage account. What you are posting is from the regular bank for checking and savings accounts which is only covered by FDIC. Those are two separate entities. The bank offers checking and savings, the Securities division offers investment and insurance solutions. Completely segregated.
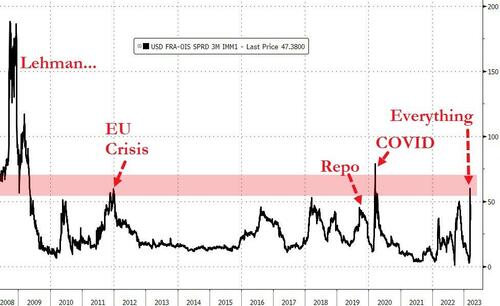
"The market stops panicking when central banks start panicking"
In January 2022, just around the time the Fed was about to launch its most aggressive tightening campaign since Volcker, we warned "remember, every Fed tightening cycle ends in disaster and then, much more Fed easing"
Fast forward to just over a week ago, when the Fed tightening cycle indeed ended in disaster when SIVB became the first (of many) banks to fail, a chain of dominoes that culminated with today's collapse of Credit Suisse - a systematically important bank with $600BN in assets.
And then, at 5pm, the easing officially began, because while a bunch of laughable macrotourists were arguing on FinTwit whether last week's record surge in the Fed's discount window was QE or wasn't QE (answer: it didn't matter, because as we said, it assured what comes next), the Fed finally capitulated, just as we warned over and over and over that it would...
"Fed either pivots too early and turns dovish in to a high inflation scenario which is fairly bearish the USD thus helping gold or they pivot too late and cause a much bigger recession than is priced in right now, resulting flight to safety helps gold." - Goldman — zerohedge (@zerohedge) [January 5, 2023]('https://twitter.com/zerohedge/status/1610851583192956930?ref_src=twsrc%5Etfw')
... and at exactly 5pm the Fed announced "[coordinated central bank action to enhance the provision of U.S. dollar liquidity]('https://www.federalreserve.gov/newsevents/pressreleases/monetary20230319a.htm')" by opening daily Dollar Swap lines with all major central banks, in a carbon copy repeat of the Fed's panicked post-covid crisis policy response playbook.
The Bank of Canada, the Bank of England, the Bank of Japan, the European Central Bank, the Federal Reserve, and the Swiss National Bank are today announcing a coordinated action to enhance the provision of liquidity via the standing U.S. dollar liquidity swap line arrangements. To improve the swap lines' effectiveness in providing U.S. dollar funding, the central banks currently offering U.S. dollar operations have agreed to increase the frequency of 7-day maturity operations from weekly to daily. These daily operations will commence on Monday, March 20, 2023, and will continue at least through the end of April. The network of swap lines among these central banks is a set of available standing facilities and [serve as an important liquidity backstop to ease strains in global funding markets]('https://www.federalreserve.gov/newsevents/pressreleases/monetary20131031a.htm'), thereby helping to mitigate the effects of such strains on the supply of credit to households and businesses.
And once the USD swap lines are reopened, the rest of the cavalry follows: rate cuts, QE (the real stuff, not that Discount Window nonsense), etc, etc. In fact, we have already seen a near record surge in reserve injections:
And this is surprising? Was surprised how far the market tanked yesterday with the Fed Announcement. I guess many investors, who felt the Fed was not going to hike the interest rate, also believe that Unicorns fart rainbows...
Hope you "Players" took some quick profits earlier today...
Shall I go to heaven or a-fishing? - H. D. Thoreau Veni. Vidi. Cepi. - with apologies to Gaius Julius Caesar
And this is surprising? Was surprised how far the market tanked yesterday with the Fed Announcement. I guess many investors, who felt the Fed was not going to hike the interest rate, also believe that Unicorns fart rainbows...
Hope you "Players" took some quick profits earlier today...
i never stay late to DA party
WHEN THE MARKET gaps up like that it usually goes back and fills it...it did that so it can still rally now into the close


 ]('
 ')